


Investors are suddenly placing a much greater emphasis on free cash flow metrics. Formerly a headwind during the second and third quarters of 2026, this is now benefiting Crawford’s quality- and dividend-oriented strategies. All Crawford strategies enjoyed a strong month in October in absolute terms and compared to the popular averages.
Free cash flow is commonly defined as the cash generated by operations after capital expenditures. It represents cash available to pay dividends, reduce debt, repurchase shares, or pursue other opportunities. Earnings growth alone, which has been very impressive this year across the market, does not capture these investment demands or the cash remaining after they are met. Our investment professionals have described free cash flow as “the lifeblood of a company.” Free cash flow is in focus because many companies have forsaken their cash flow to invest in the AI buildout. We will explore the topic throughout this update.
For much of this year, extraordinary growth in earnings and forward expectations drove strong returns in AI-related companies, overshadowing the predictable earnings, consistent cash generation, sustainable dividends, and reasonable valuations in businesses we favor. Rising interest rates also reduced the present value of expected future cash flows, which initially pressured valuations of more mature, stable companies. Surging earnings expectations, largely related to AI, helped some of the fastest-growing companies offset that pressure for some time. Steadier businesses had less of an offset, even as their fundamentals remained strong and, in many cases, improved. This dynamic weighed on our relative performance for much of 2026. By design, we did not own the semiconductor and energy stocks where cyclicality drove much of the market’s gains, nor the most richly valued AI leaders.
Treasury yields have eased in October, providing some relief from valuation pressure. At the same time, investors have become increasingly discerning and are now focused on the negative aspects of an extended period of negative free cash flow projected for several major AI infrastructure spenders. This has implications for the broader AI subset of the market today. Together, these developments have been more supportive of the cash-generating businesses we favor.
Capital expenditures are absorbing more than 100% of operating cash flow for most of the hyperscalers, the large technology companies that operate vast cloud computing and AI infrastructure. These companies must therefore raise equity and debt in the capital markets to meet their cash needs. Quite suddenly, the market has begun to question how long that reliance on external financing can continue. To be fair, the companies involved expect to generate high returns on these investments over time. Based on consensus estimates, free cash flow for the large hyperscalers will bottom in the third quarter of 2027 at about -$265 billion. That is roughly a $440 billion swing in under four years. Equally important, the aggregate free cash flow is forecasted to recover to nearly $505 billion by 2030, as depicted in the chart below. This bears careful attention.
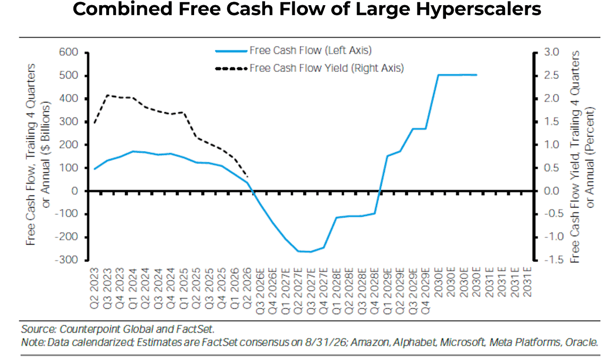
The projected recovery of free cash flow depends on future demand and profitability justifying today’s spending. If the payoff falls short, takes longer to materialize, or if AI users seek out more cost effective solutions, financial flexibility can erode even as reported earnings grow. This is a risk factor that is beginning to manifest in a number of AI companies, many of which are now experiencing a bear market in their share prices (down -20% or more).
Our investment team seeks businesses generating sufficient cash to fund their operations, invest for the future, and support sustainable dividends, with less reliance on external financing. We assess cash generation alongside competitive strength, capital allocation, and valuation to determine whether growth is creating lasting shareholder value. We are unwilling to compromise these standards to pursue short-term trends that sometimes create the stock market’s strongest performers. Free cash flow has remained central to our approach throughout this year, and we are encouraged to see the market beginning to reward this discipline. We remain committed to the standards that have guided our investment decisions across a number of varied market environments.
Disclosures:
Past performance is not indicative of future results. All investments involve risk, including loss of principal and there is no guarantee that investment objectives will be met. The opinions expressed are those of Crawford Investment Counsel as of the date of publication and subject to change without notice. Crawford Investment Counsel is an investment adviser registered with the U.S. Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about Crawford Investment Counsel’s investment advisory services can be found in its Form ADV Part 2 and/or Form CRS, which is available upon request. CRA-2611-1

March 2024 | Quarterly Letter
Currently, the good news on the economic and market fronts makes us optimistic about the future, but we also need to keep in mind the risks to the outlook.

June 2024 | Quarterly Letter
Currently, the good news on the economic and market fronts makes us optimistic about the future, but we also need to keep in mind the risks to the outlook.

February 2021 | Mid-Quarter Update
We are pleased to forward our mid-quarter update on developments within the economy and financial markets.

